Owning a home now costs the typical U.S. homeowner $16,566 a year beyond the mortgage payment, according to a new analysis from Zillow and Thumbtack released Thursday.
That works out to about $1,380 a month for maintenance, property taxes and homeowners insurance. That’s up 32 percent over five years, or roughly $4,000 more a year than owners paid in 2021.
The report notes that the pace of homeownership cost increases is cooling. Those costs rose just 3 percent over the past year, suggesting the post-pandemic run-up in ownership costs is losing steam. In most markets, insurance is the big exception.
Maintenance cools, insurance climbs
The analysis covers 30 of the largest U.S. metros, and Zillow estimated annual property tax and insurance costs for a typical homeowner in each market. Thumbtack, an online local-services marketplace, supplied the maintenance figures. It’s a weighted index of recommended yearly projects, priced from jobs requested on its platform and calculated quarterly using a moving average.
Kendra Sinclair
Maintenance makes up the bulk of the bill: $11,171 a year, about two-thirds of the national total. Property taxes add $3,129 and insurance adds $2,266.
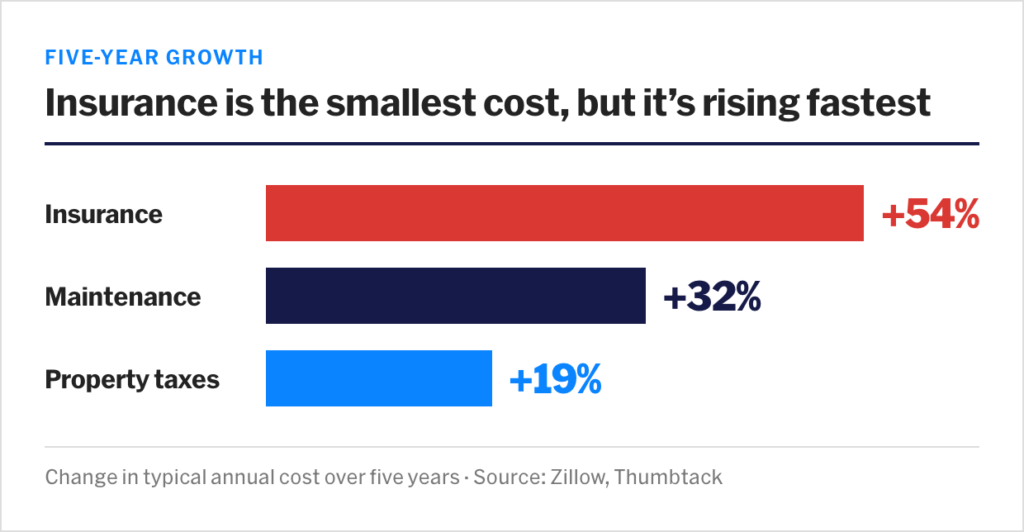
Insurance is the smallest of the three, but it’s growing fastest. Premiums are up 54 percent over 5 years, compared with 32 percent for maintenance and 19 percent for property taxes.
Maintenance shows the clearest slowdown. Annual increases have shrunk every year, from 9 percent in 2022 to 1 percent in 2026.
“The slowdown in maintenance cost growth is welcome news for homeowners managing a lot of competing expenses,” said Kendra Sinclair, Thumbtack’s home trends expert, in a statement. “Planning for regular upkeep throughout the year can help prevent bigger repair bills and protect your savings when something unexpected happens.”
Zillow suggests insurance costs may slow next, pointing to federal data showing premiums rose just 0.3 percent between February and June 2026. Premiums, however, still sit well above where they were 5 years ago.
Note: Image built with AI assistance
Insurance premiums up 50% in 19 metros
The insurance surge has hit some markets much harder than others. Premiums are up at least 50 percent over 5 years in 19 of the 30 metros analyzed, led by Dallas at 75 percent, Tampa at 71 percent, Denver at 70 percent and Houston at 69 percent.
Miami homeowners pay the most, at nearly $5,000 a year. Six metros now top $3,000: Miami, Dallas, Houston, Tampa, Orlando and Denver.
In four metros — Houston, Phoenix, Denver and Nashville —, homeowners now pay more each year for insurance than for property taxes. Zillow attributes much of the increase in storm-prone metros like Dallas and Denver to severe weather, including hail, tornadoes and damaging winds.
Coasts cost most, LA climbs fastest
The coasts have the highest total costs: $25,111 in New York, $24,383 in San Francisco, $22,915 in Los Angeles and $22,096 in Boston. Phoenix is the cheapest market in the analysis, and it still runs $14,187 a year.
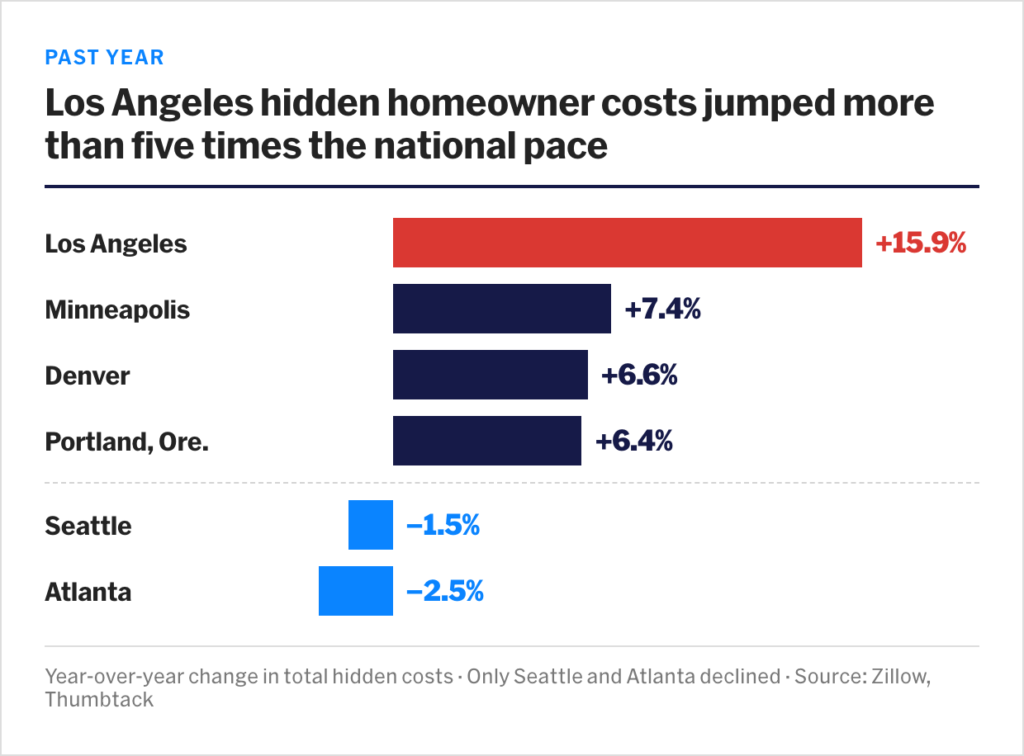
Los Angeles is the clear outlier on recent growth. Total hidden costs there jumped 15.9 percent year over year, more than five times the national pace. A 27 percent increase in maintenance costs drove the jump, which the report attributes to wildfire recovery, heavier demand for home services and persistently high labor costs.
Minneapolis (7.4 percent), Denver (6.6 percent) and Portland, Oregon (6.4 percent) also outpaced the nation over the past year. Only two metros saw costs fall: Atlanta, down 2.5 percent, and Seattle, down 1.5 percent.
The five-year data tells a different story. Pittsburgh posted the biggest increase of any metro at 54.8 percent, though the release doesn’t call it out. Tampa (44.4 percent), Miami (42.8 percent) and Los Angeles (42.5 percent) followed.
Note: Image built with AI assistance
A caveat, and a takeaway for agents
The maintenance figure deserves a caveat. Thumbtack’s $11,171 doesn’t reflect what the typical owner actually spent last year. It’s an index of what recommended upkeep would cost at Thumbtack pricing. Owners who defer projects or do the work themselves are likely spending less.
Kara Ng
Both companies also sell products here. The release steers buyers toward Zillow’s BuyAbility affordability tool and Thumbtack’s maintenance guides.
Even so, the data aligns with what agents in high-premium markets have dealt with for years: purchase price is only part of affordability, and carrying costs vary widely by metro.
For agents, the most practical takeaway is to bring insurance numbers into the conversation before the offer, not after inspection. Zillow advises buyers to get a quote on a specific property before bidding, since the premium can change what a buyer can afford.
“Many households focus so much on winning the home and underestimate what it costs to live in it,” Kara Ng, a senior economist at Zillow, said in a statement. “Since these homeownership costs vary so much by market, homeshoppers should run the numbers and understand what they can truly afford before they make an offer.”