Homebuyers aren’t the only ones flocking to the Midwest.
Secondary markets across Illinois, Ohio and Wisconsin are proving to be short-term rental gold mines, with investors facing less competition for affordably priced homes. AirDNA, which tracks and analyzes Vrbo and Airbnb data, identified the 17 best short-term rental submarkets: 400 to 1,000 listings, an annual yield of more than 10 percent and a small share (<20 percent) of professionally managed properties.
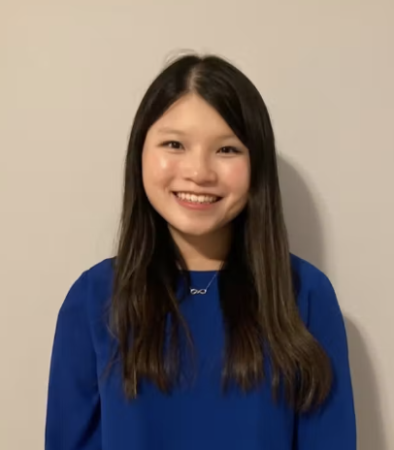
Linda Rollins
“This is a great list. There are so many markets that have affordable home prices,” AirDNA Senior Research Analyst Linda Rollins told Realtor.com, which had the exclusive. “With mortgage rates being so high, it’s so hard to justify investing. … But when you do have an area where home prices are still affordable, you could make a decent down payment and still be able to see those numbers work.”
Rockford, Illinois, led the list, with a yield of 14 percent, based on an average home value of $300,442 and annual revenue potential of $40,024. The number of short-term listings in the area, which is 90 minutes northwest of Chicago, has grown 13 percent year over year.
However, AirDNA said the revenue per available room (RevPAR) is still growing at 6 percent year over year, meaning there’s still plenty of opportunity for investors to net healthy gains, despite double-digit percentage growth.
“Professional management is effectively absent from [Rockford], which means an individual host is not competing with a local management company for bookings,” the report read.
Akron, Ohio, and Warner Robins, Georgia, rounded out the top three, with yields of 13 and 12 percent, respectively. Both markets have average home values under $325,000 and annual revenue potentials around $40,000. Like Rockford, Akron and Warner Robins’ RevPARs are still growing, even as annual short-term listing growth exceeds 10 percent.
Utica, New York; Otsego Lake, Michigan; Lawton, Oklahoma; Millersburg, Ohio; Midland, Texas; Geneva, Ohio; Castle Rock Lake, Wisconsin; Houghton, Michigan; Michigan City, Indiana; Gary, Indiana; Manhattan, Kansas; Terlingua, Texas; Nolin River Lake, Kentucky; and Dunnellon, Florida; rounded out the list, pinpointing the Midwest and South as the best regions for short-term rental investors.
While these markets might not have the amenities and entertainment of larger locales, AirDNA’s researchers said they still draw a steady stream of demand from city dwellers seeking a brief respite from the hustle and bustle of everyday life. These submarkets, they said, are often also near military bases, which also buoy interest.
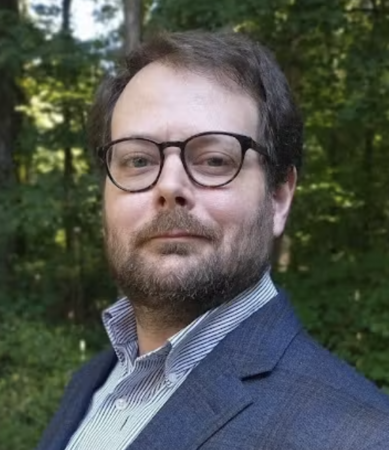
Bram Gallagher
“Travel is a really repeat business. People go out and visit national parks; they come back with their slideshows, and they show all their friends,” AirDNA economist Bram Gallagher told Realtor.com. “The affordability, combined with the unique demand generators, [is] regularly pulling people into some of these markets.”
Midwesterners might not be happy to find that short-term rental investors are eyeing their region, which is already grappling with the effects of heightened attention from homebuyers priced out of New York City, Los Angeles and other coastal hubs.
Inman‘s latest report on the Midwest revealed that housing costs in the region are, on average, about 30 to 50 percent cheaper than the West and East. However, the influx of buyers — primarily millennials and Gen-Zers — is putting affordability at risk in the region’s most popular cities: Chicago; Columbus, Ohio; Indianapolis; Detroit; Milwaukee; Kansas City; Minneapolis; Cleveland; and St. Louis.
Right now, affordability is holding steady in the region, with the Midwest ranking third in the National Association of Realtors’ August Housing Affordability Index (+1.7 percent) behind the West (+5.9 percent) and South (+4.5 percent).
As for how short-term rentals might influence the tender balance between supply and demand, research is split.
While current statistics suggest that institutional buyers have a negligible impact on the for-sale market, as their portfolios account for less than 1 percent of the housing stock, city leaders are still cracking down on short-term rentals. Salt Lake City is the latest to lower the hammer, now requiring short-term rental owners to get licensed and pay an annual fee.
Airbnb recently launched a $250 million affordable housing fund, as the company continues to bat off claims that its business model has exacerbated costs for homebuyers in supply-constrained markets. “The housing crisis wasn’t created overnight, and it won’t be solved overnight,” Airbnb CEO Brian Chesky said. “But we can start moving in the right direction.”