The Fed is raising rates again, inflation is still running above target, and mortgage costs are putting pressure on the housing market. Here’s a look at the latest numbers and what they mean for the market this fall.
Rising interest rates
The first number to know this month: a quarter point. That’s how much the Federal Reserve Open Market Committee just voted to raise its target for the overnight Federal Funds Rate, announced at its meeting on Sept. 16.
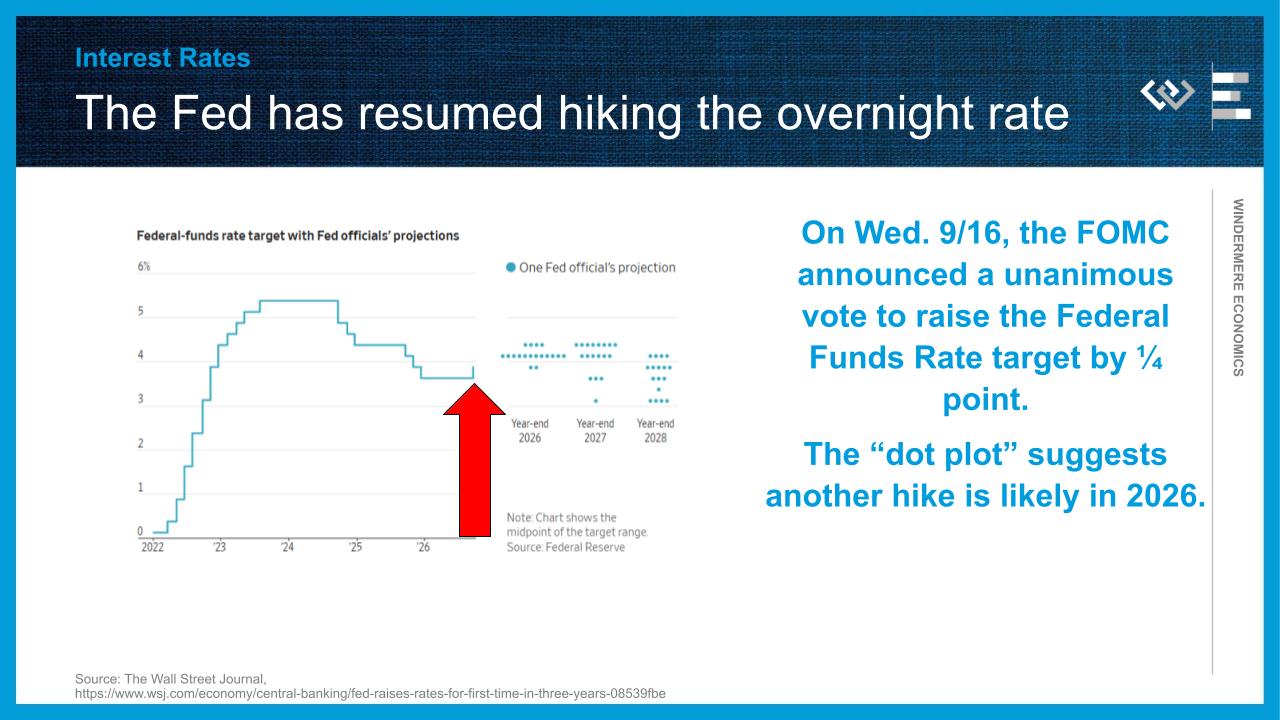
It’s the first hike since 2023, when the Fed completed a dramatic hiking cycle from essentially 0 percent to over 5 percent, and it brings the upper end of their target range back up to 4 percent.
The Summary of Economic Projections from committee members suggests it’s likely not the last hike we’ll see from the Fed this year, as the median member expects the appropriate rate by the end of the year to be another quarter point higher.
Why is the Fed pivoting from cutting to hiking? One major reason is our next number to know: the inflation rate, which stood at 3.4 percent year-over-year in August, or well above the Fed’s target of 2 percent.
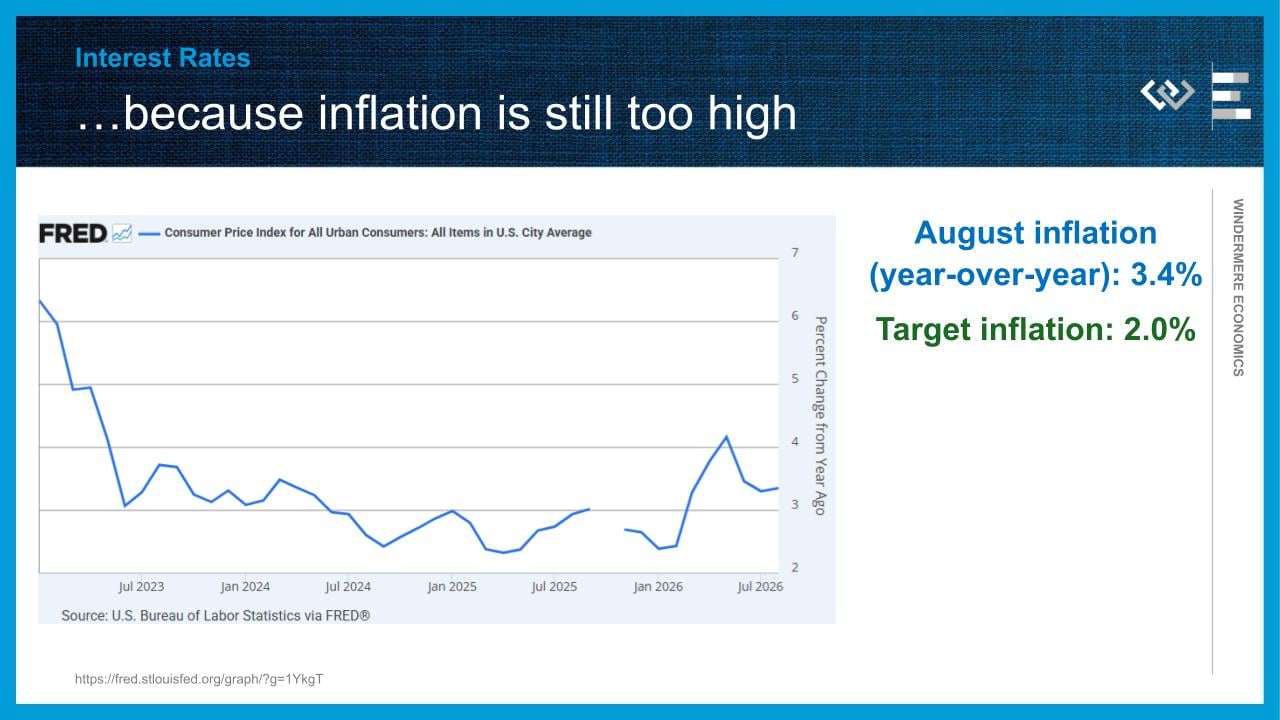
Since economic data from the labor market and overall economic growth have all looked stronger this summer, the Fed is understandably turning its attention back to fighting inflation, as the new chairman Kevin Warsh promised when he was appointed this year.
The 10-year Treasury yield
The next number to know this month: 5 percent. That is the yield that 10-year Treasuries reached on Sept. 15, now the highest in two decades. All around the world, we are seeing higher borrowing costs, thanks to higher inflation, a strong investment boom driven by AI and huge amounts of debt issued by governments running deficits.
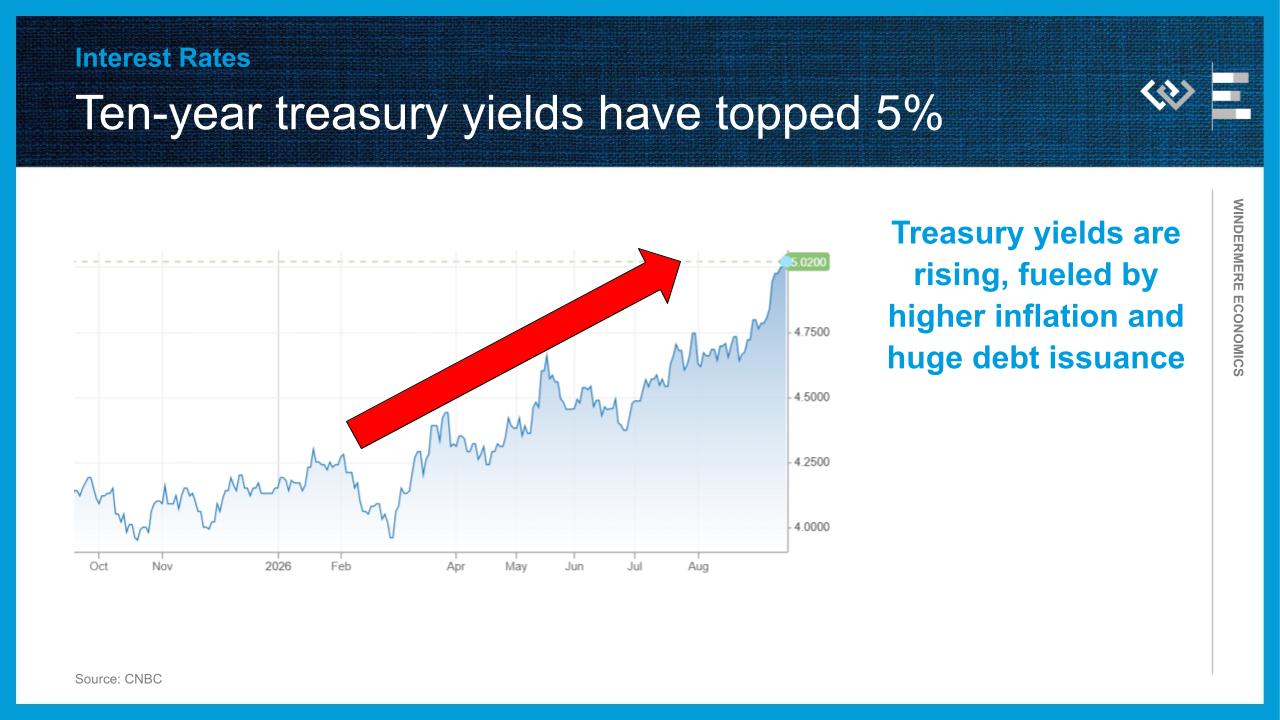
The 10-year Treasury is usually a benchmark for mortgage rates and now, depending on the source, mortgage rates stand as much as a full point higher than last year: at roughly 7 and a quarter percent, according to Mortgage News Daily. There is no question that high mortgage borrowing costs are slowing housing market demand this fall.
Active listing inventory numbers
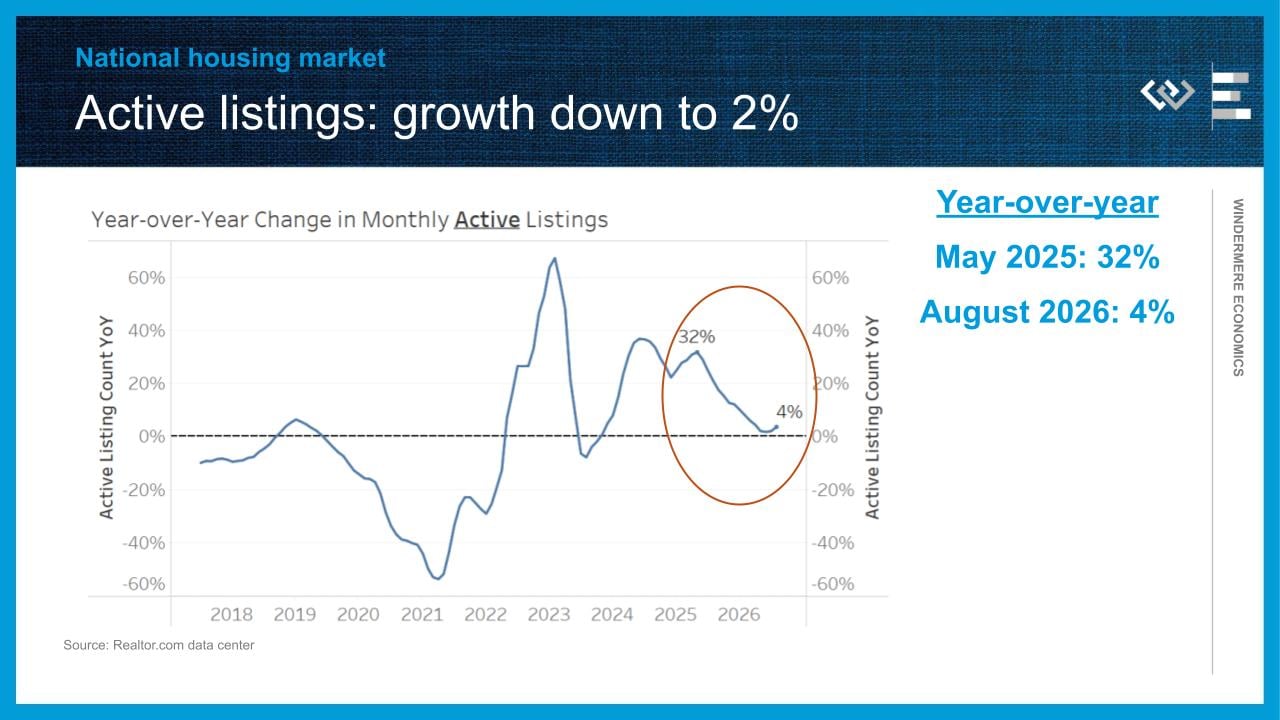
The fourth number to know: 1,140,000. That is how many active listings were on the market nationally at the end of August, according to Realtor.com. That is just above the 1.1 million active listings in August of last year.
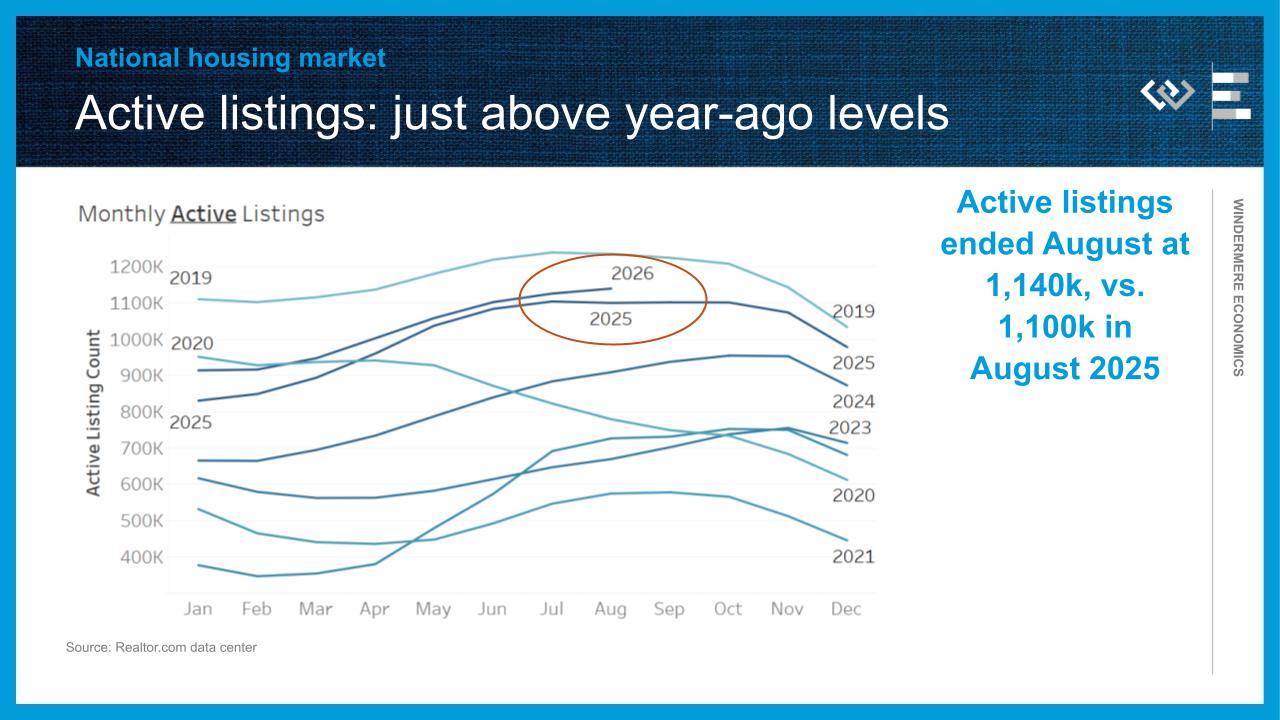
You can see a bit of a gap opening up, and that’s reflected in our next number: 4 percent, which was the year-over-year growth in active listings. It may represent a turning point, where buyers are shying away, leaving a growing pool of inventory on the market, which should cool down price appreciation this fall.
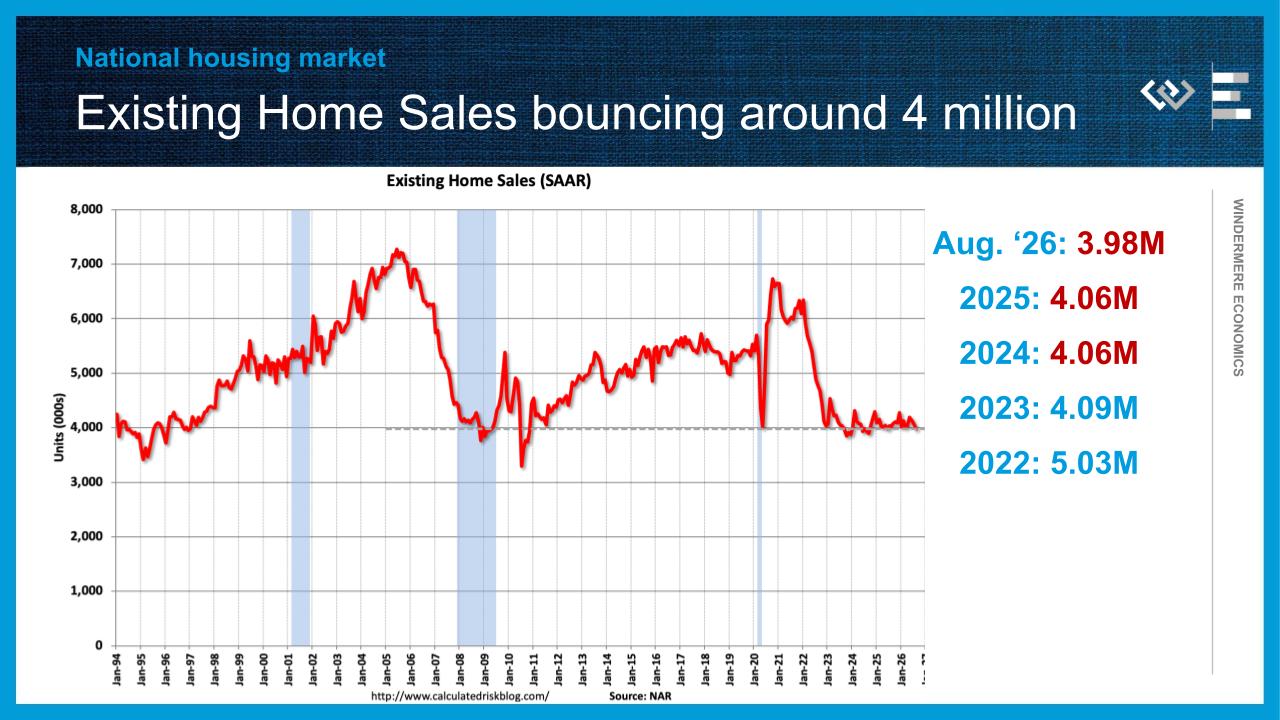
Finally, the NAR reported disappointing August existing-home sales at a 3.98 million annualized run rate, slightly below the pace it was running earlier in the summer. That’s another sign that the run-up in mortgage rates is beginning to drag a little bit on home purchase demand.
Looking forward, the combination of diminished purchase demand and higher inventory should mean extra favorable conditions for those buyers who can afford to forge ahead with purchases this fall. But it means a little bit more difficult selling conditions for those 1.14 million folks trying to sell a home right now.
 Money Matters Month is here. All September, Inman is focused on the financial side of real estate — the part nobody teaches you when you get your license. How to budget through lean times, protect your profits when business is good and find new ways to grow your bottom line no matter what the market is doing.
Jeff Tucker is the Principal Economist for Windermere Real Estate in Seattle, Washington. Connect with him on X or Facebook.