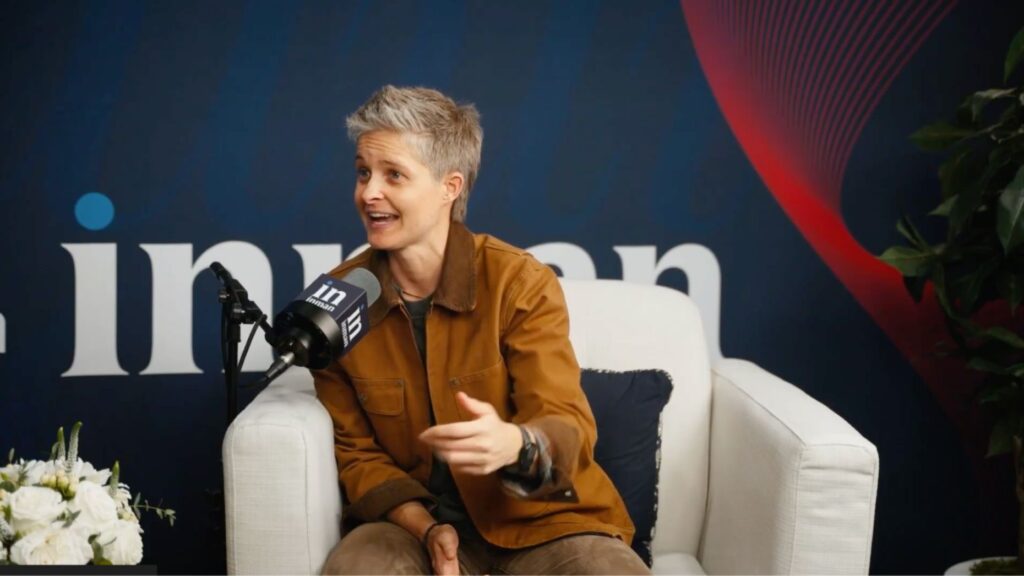
It only takes a Saturday to learn more about creative financing, according to Mel Dorman, author of Bank on Your Neighbor and founder of the Seller Finance Academy, a real estate investing course. Some agents are afraid to learn the ins and outs of seller financing, but in an environment where interest rates are holding steady around 7.4 percent, alternatives to traditional lending are key.
“The higher the rates go, the better it is for anybody who knows about creative financing,” Dorman told Inman’s Taylor Anderson at eXp Con.
“Agents who are at the forefront of this, who are paying attention, learning these skills, being able to talk to sellers about their full array of options, those are the folks that are doing really well,” she said.
Dorman, who’s no longer a practicing Realtor, said she’s still getting calls from people asking how to solve these problems.
A quick explainer: With seller financing, the seller becomes the bank “and you’re making your payments directly to them each month instead of Wells Fargo or Chase,” Dorman said. “And when you do that you get to structure the terms however you both agree to them. You get to choose your own interest rate, you get to choose your downpayment size — whatever is good for the buyer and seller.”
As soon as interest rates increase, “Americans remember that they can work together directly and they overcome these high interest rates,” she said.
Some terms to know
- The wraparound mortgage (or wrap note). This is a formal type of seller financing. The seller creates a new, junior mortgage that “wraps around” their existing loan and acts as the lender in the transaction. The buyer makes monthly payments to the seller, who uses part of that money to keep paying the original mortgage and often pockets the difference between the two interest rates.
- “Subject to” (or sub-to). In this arrangement, the buyer takes title to the property and makes the payments on the seller’s existing mortgage. The buyer doesn’t formally assume the loan with the lender, and the seller doesn’t create a new note. Dorman cautioned that the transfer could trigger the loan’s due-on-sale clause, which would let the lender “call due” the full balance.
In both arrangements, the original mortgage stays in the seller’s name. If payments stop, the seller’s credit is at risk, and in either case the lender could invoke a due-on-sale clause. As such, both require a close look at the existing loan and sellers should consult real estate attorneys.
Finding the right sellers — usually with no underlying mortgage
Most of the time, sellers who offer seller financing don’t have an underlying mortgage — or if they do, they’re unable to pay it and are facing foreclosure unless their debt is taken over. You see both scenarios regularly, Dorman said.
“Four out of 10 homes are actually paid off free and clear, so there’s a lot of inventory — the most we’ve ever seen in the United States in all of history, so it’s an excellent time to go search for people and say, ‘Hey, can I turn your equity into an income stream? Are you ready to downsize or retire?’ You’re looking for tired landlords; you’re looking for people who have a problem to solve, and they don’t need a lot of cash right now. They’d rather have more cash later.”
Dorman sees potential among landlords who want to stop handling repairs and tenants while continuing to receive monthly income. These sellers are also gonna save a lot in taxes on the original home, sweetening the deal for them.
Getting compensated as an agent
Some agents worry that a sale without a conventional mortgage will leave them without a commission. According to Dorman, they shouldn’t worry.
Agents can receive a commission from the down payment, provided enough cash is available at closing to cover the agreed compensation and expenses, she said.
Dorman argues that favorable financing can give a buyer flexibility to meet a seller’s asking price — and sometimes go even higher.
“Usually the buyer can pay a top dollar because they’re going to get a better interest rate,” she said.
She cited a recent transaction involving a Muslim buyer who wanted to avoid paying interest and took a zero percent loan. According to Dorman, the seller agreed to a zero-interest loan in exchange for about $175,000 on top of the price.
“Being able to negotiate the terms person-to-person just opens up a huge creative toolbox, and you can design it however you need to meet both people’s needs.”