There is no question that today’s housing market is challenging. Inventory remains tight in many places. Interest rates continue to shape buyer behavior. Sellers are still adjusting to a market that no longer feels like the peak years of 2021, 2022 or even 2023.
Whenever there is broader economic uncertainty, many buyers and sellers naturally step back and wait for more clarity.
But from where I sit in the trenches of the housing market every day, I see another story unfolding. Hispanic homebuyers are not sitting on the sidelines. They are finding ways to persevere, adapt and keep moving toward homeownership. In many markets, they are not just participating in the housing economy; they are helping carry it forward.
Consider these statistics from the 2026 State of Hispanic Wealth Report just released by the National Association of Hispanic Real Estate Professionals (NAHREP) and Hispanic Wealth Project ahead of Hispanic Heritage Month: Hispanic owner-households reached a record 10.2 million in 2025, accounting for all net growth in U.S. homeownership last year.
Without Hispanic homebuyers, American homeownership would have declined. Hispanic families also formed 92.6 percent of all U.S. household growth.
The significant impact of Hispanic homeowners is an important distinction for our industry to understand. Too often, we talk about the housing market as though all buyers are responding to the same pressures in the same way. They are not.
The Hispanic market has its own dynamics, its own motivations and its own strategies for overcoming affordability challenges. If real estate professionals, lenders and policymakers want to understand where housing demand is headed, they need to understand this community.
Homeownership is a family strategy
One of the clearest examples is the rise of multigenerational homebuying. In my Southern California market, roughly one-third of the Hispanic buyers we are seeing are purchasing homes this way.
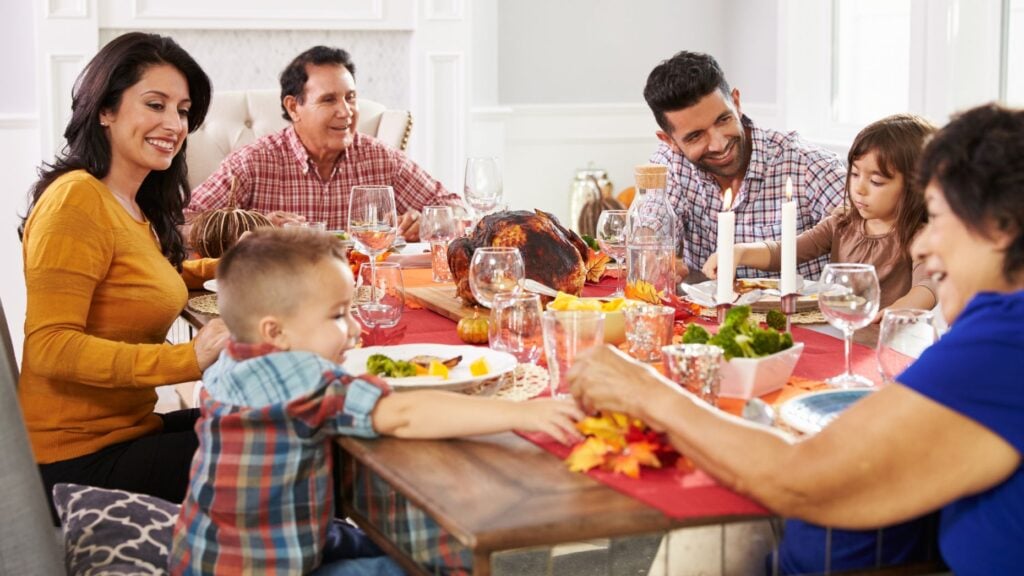
It is not always the traditional first-time buyer profile of one young couple buying a starter home. Instead, we are seeing parents, adult children, grandparents and sometimes younger children planning together, combining incomes and choosing homes that can support the whole family under one roof.
For many Hispanic families, this is not simply a response to high prices. It is also rooted in culture. Family is central. Caregiving is central. Building legacy is central.
When a family sits around the dining room table and asks, “Can we qualify together? Can we manage the payment together? Can we live together and build something together?” they are not just evaluating a transaction. They are creating a long-term family strategy.
That requires our industry to think differently. A home may need to work for multiple generations. The buyer consultation may include several decision-makers. The conversation may involve more than bedrooms, bathrooms and square footage; it may involve caregiving, shared financial responsibility, household stability and wealth creation.
Payment matters more than the rate
Affordability is real. Hispanic buyers are facing the same headwinds as every other buyer: higher prices, higher borrowing costs and limited inventory. But many of the buyers I work with are not making decisions based only on the interest rate. They are focused on the payment.
When several income earners are contributing to the household, the monthly payment becomes a shared responsibility. That changes the equation. A higher rate or a larger home may still be workable if the family can divide the payment in a way that feels manageable. This does not mean affordability pressures disappear; it means Hispanic buyers are often finding practical ways to navigate them.
For agents and lenders, this is a critical lesson. We cannot serve today’s buyers well if we only present one version of the American dream or one path to financing it. We need to understand what buyers are trying to accomplish and then help them evaluate the options that fit their real circumstances.
Financing must reflect how people actually earn
Another area where the industry needs to evolve is financing. Many Hispanic buyers are entrepreneurs, small-business owners, independent contractors or self-employed workers. They may have a strong income, strong work ethic and a clear desire to own a home, but they may not fit neatly into a conventional W-2 underwriting box.
That means agents and lenders need to be fluent in more than conventional loans. FHA financing, verification-of-employment programs, profit-and-loss statement loans, debt-service coverage ratio products, non-QM options and bank grant programs may all be part of the conversation. The point is not to push a product. The point is to understand the buyer’s income reality and help them see what may be possible.
Too many potential homeowners still believe they need 20% down before they can buy. That misconception alone keeps people from taking the first step. Our responsibility as professionals is to replace confusion with education and fear with informed choices.
The new mainstream requires a new industry mindset
At NAHREP, we often say the Hispanic market is the new mainstream. That statement is not just about demographics. It is about where future household formation, homebuying demand and community wealth creation are headed.
The question is whether the industry is ready. Hiring bilingual agents is important, but language is only one piece of the equation. Professionals also need cultural fluency. They need to understand family dynamics, how decisions are made, what buyers value and why homeownership carries such deep meaning for many Hispanic families.
Brokerages and lenders should be asking hard questions: Does our marketing speak to this consumer? Do our agents understand multi-generational buying? Are we educating buyers on a full range of financing options? Are we showing up where first-time buyers are actually looking for information?
Education is the bridge to opportunity
One of the biggest gaps I see is access to trusted, practical guidance. Many Hispanic first-time buyers do not have a family agent who helped their parents buy a home. They are the first generation taking on this journey and are starting fresh. Increasingly, they are turning to social media, community events and local professionals who are willing to educate before they sell.
That creates a tremendous opportunity for real estate professionals, especially newer agents. The agents who are building trust today are not just posting listings. They are explaining the process. They are sharing buyer success stories. They are creating short, useful content about down payments, inspections, loan products and common mistakes. They are showing people that homeownership may be closer than they think.
To become a trusted guide, agents should be educating themselves to better serve the unique needs of this community. They need to proactively commit to growing their expertise. There is tremendous value in being an ally to the Hispanic community, even if they don’t identify as Hispanic themselves.
Consumer education has to happen in the places where buyers already are: online, in their communities, at seminars, at open houses and through trusted relationships. When we make information accessible, we help families move from uncertainty to action.
Policy must help unlock movement in the market
The private sector has work to do, but so do policymakers. If we want a healthier housing market, we need policies that increase inventory and make homeownership more attainable. That means looking seriously at the barriers keeping current homeowners from selling, including tax consequences and the fear of losing favorable property tax treatment.
For example, outdated capital gains exclusions can discourage long-time owners from moving, especially in high-cost markets. Property tax portability policies, like those available to some older homeowners in California, can also influence whether people feel able to sell and right-size. When sellers stay locked in, inventory remains constrained. When policy helps remove friction, more homes can come to market, and more families can find opportunity.
Housing policy should not be abstract. It should be measured by whether it helps real families move, buy, build wealth and participate in the economy.
Hispanic homeownership is a national economic story
When we talk about Hispanic homeownership, we should not treat it as a niche topic. This is a national housing story. It is an economic story. It is a wealth-building story. And it is a preview of where the future of real estate is going.
I’m proud to work with both NAHREP and the Century 21 brand to expand our industry’s mindset with that future in mind. As we look to build bridges between real estate professionals in the United States and Latin America, we are recognizing that Hispanic wealth, mobility and investment are increasingly global. Families are building equity here, considering opportunities abroad and creating new pathways for generational wealth.
The opportunity in front of us is enormous. But we will only meet it if we listen closely, adapt intentionally and serve this market with the respect, knowledge and urgency it deserves. Hispanic homebuyers have already shown they are ready to move forward. Now the industry must be ready to move forward with them.