John Moore needed a new home.
His 11-year-old daughter told him that she and her two siblings needed more space. And what else is a loving dad supposed to do but contact a buyer’s agent and start scouring listings for the best, kid-approved abode? The search proved more difficult than Moore anticipated, though, with Denver’s market more expensive and competitive than the first time he bought a home with his ex-wife.
“I was really looking for the opportunity to live in a place close to my kids and make life sort of as easy as possible for them, too,” he said. “But the market, specifically the areas I wanted to live in, has been sort of disproportionately aggressive in terms of the cost of housing. So the house that we had previously, and the equivalent now, is out of reach. But that was not really a scenario that’s suitable for three kids.”
The math simply wasn’t working until Moore’s agent, Brian Anders, told him about Estately, a new real estate solutions company co-founded by former Coldwell Banker Real Estate President M. Ryan Gorman and Bill Young.
Estately reduces a homebuyer’s monthly payment by splitting the listing price: 60 percent for the home and 40 percent for the land.
When the buyer applies for a mortgage, the loan and down payment are based only on the home’s value (60 percent). Meanwhile, Estately purchases the land beneath the home and drafts a 50-year lease with a fixed rate lower than the mortgage. The mortgage and lease are bundled into one monthly payment, and the lease payment adjusts annually with changes in the Consumer Price Index (CPI).
Ultimately, Estately estimates its model can save buyers up to 20 percent on initial monthly payments and up to 40 percent on their down payment. Estately provides exact savings on each listing and provides a payment calculator that factors in their down payment, mortgage rate and inflationary trends, such as historically high or low CPI growth.
Moore reviewed Estately’s calculators, completed a required training on land leases with Estately’s participating lender, Guild Mortgage, and spent a few hours working through the math himself, drawing on his extensive finance background. At the end of the day, the terms of the deal made sense — and Moore was able to reduce the down payment by $45,000 and the monthly payment by $650 on his $625,000 home.
“When it comes down to it, if you borrow $100,000 and 50 percent is being charged an interest rate of 8 percent and 50 percent of it is being charged an interest rate of 5.5 percent, versus all of it being charged an interest rate of 8 percent — which would you choose?” he said. “It made it feasible to purchase, whether it was buying within the neighborhood and scaling up in a house or buying a house and doing some updates that might make it more welcoming for my kids.”
M. Ryan Gorm
Remixing an existing system
In a phone call with Inman, Gorman said Estately stems from the housing policy and affordability work he’s dedicated himself to since the end of his presidency at Coldwell Banker Real Estate in 2022. He and Estately co-founder Bill Young tossed around business ideas for nearly four years, before zeroing in on land leases.
Land leases have existed in the United States since the 18th century, with Congress passing several ordinances and acts in the last decades of the 1700s to formalize individual land ownership rights. The use of land leases — which are not the same as land contracts that withhold ownership rights until the contract is paid off — has evolved since, with the most common uses being for residential properties on federally or state-owned tracts of land or community land trusts.
However, land leases haven’t taken off in the U.S. residential market as they have in other countries across Central and South America, Europe, Southeast Asia, Africa and the Pacific, where leases commonly range from 50 to 100 years.
Gorman and Young latched onto the idea of introducing land leases to the wider market, “riding on existing rails” of the system that allows government-sponsored enterprises to purchase or secure loans on leasehold mortgages. They also reviewed years of annual reports from the Federal Housing Finance Agency (FHFA) and the American Enterprise Institute (AEI) on land values, which helped them develop the 60/40 split.
The duo believed that land leases could help buyers in the middle of the market — professionals who made too much to qualify for homeownership grants and funds, but still didn’t have enough to compete with buyers with high incomes.
“We wanted everyone to have an opportunity to live where they wanted to live,” he said. “[The government] already developed programs for that subset, and we were able to design a program that complies with and utilizes that design, so we’re not reinventing the wheel and asking the entire system to act differently.”
It’s all about the monthly payment
Estately currently works with one participating lender, Guild Mortgage, for its leasehold mortgages.
Gorman said all Guild Mortgage loan officers complete a rigorous training on Estately’s land lease program, so they’re able to work through the nuances of what homebuyers must consider — such as mortgage insurance premiums, how the lease factors into the mortgage payment, what happens if they default on land lease payments, whether they can ever get a Home Equity Line of Credit (HELOC) or second lien (the answer is yes) and how refinancing the mortgage works.
“[The officers] can help evaluate your options, one of which is an Estately land lease, and there may be others,” he added. “But we have a plethora of tools on our site, like calculators and FAQs and video explainers and all kinds of different scenario builders to help buyers understand their choices. You know your situation better than anyone else. Put your assumptions into our calculators and see whether or not the results are things that are exciting to you.”
Among the nearly 2,000 Estately-qualified listings in Denver, the monthly savings range from $1,570 for a $1.135 million home to $567 for a $410,000 townhome, assuming the buyer provides a minimum down payment of 3 percent and secures a 30-year-fixed-rate loan at the current average of 7.648 percent.
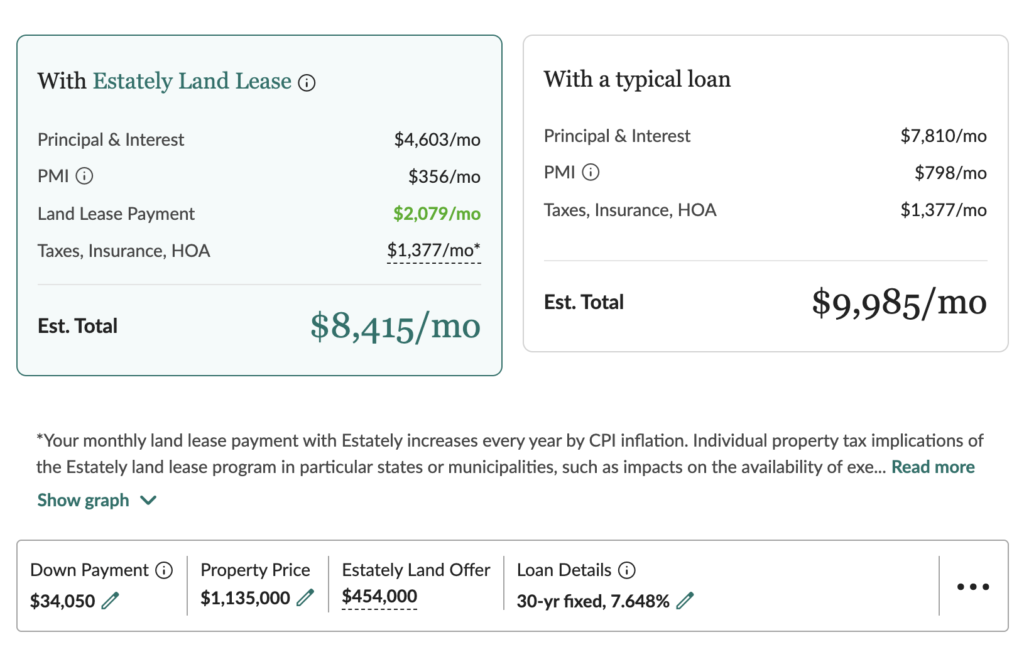
A screenshot of Estately’s affordability calculator for a $1.135 million listing. The buyer pays $681,000 for the home, and Estately pays $454,000 for the land.
Gorman said those monthly savings can give homebuyers an edge, letting them pad their savings or pay off their mortgage earlier.
“Payments are the constraint, and that is both the down payment and the monthly payment,” he said. “We designed Estately Land Lease to really go after both of those two payments and try and make them more manageable for folks. For most people, as they think about their overall affordability journey, payments are their primary consideration, and so that’s really what we’ve focused on trying to deliver to get them into homeownership.”
Homebuyers can refinance their mortgage, and Estately allows them to buy the land outright at any time for an adjusted amount that accounts for payments already made, transaction costs and CPI increases.
When they’re ready to move, they can sell the home and land together and keep the remaining proceeds after paying off the mortgage and the adjusted land price, or they can sell the home and transfer the lease to the new homebuyer. Any appreciation on the land above inflation belongs to the homeowner, Estately explained.
Opening doors
Moore said the closing process was similar to the first time he purchased a home, except for the addition of “six or seven more signatures” for the documents related to the lease. Since closing, he’s told family and friends who are also struggling to grapple with today’s affordability landscape to consider Estately’s program and see if the math works for them.
“It opens up doors that didn’t exist otherwise,” Moore said. “… From a wealth standpoint, people’s ability to compile wealth from homeownership versus renting is significant. I work in healthcare; when you think about the ability to own your own place, there are a lot of things that splinter off from that that are actually health-related, right? It’s all very intertwined.”
Gorman said Estately is in the early stages of growth, with operations expanding from Colorado to Texas just this month. They plan to launch operations in Washington, Oregon, California and Utah soon and will expand the list of participating lenders.
“We designed Estately Land Lease so the homeowner is always in control,” he said. “We are transparent through every step of the home purchase and land lease experience, including clear education, pricing and terms, empowering consumers to make successful homeownership decisions with confidence.”