Perhaps in keeping with the Halloween season, the market has a number of tricks — and treats — up its sleeve for buyers this fall.
Realtor.com’s quarterly Market Clock moved to 4 p.m., as two-thirds of the 99 metros the portal tracks now favor homebuyers. The Market Clock measures market balance based on inventory, sales and contract activity, with 12 p.m. being peak seller, and 6 p.m. being peak buyer.
Seventeen markets are outright buyer’s markets, according to Realtor.com, while 49 are balanced and loosening in buyers’ favor. Twenty-seven markets are seller’s markets, and six are balanced and tightening. Compared with the second quarter of 2025, seller’s markets fell from 39 to 27, while buyer’s markets rose from 13 to 17.
Regionally, sellers have the most leverage in the Midwest, while buyers have the upper hand in the South. The West is moving toward purchasers, with the region gaining three new buyer’s markets: Bakersfield, Colorado Springs and Riverside.
At the metro level, Austin, Texas; Seattle, Washington; Salt Lake City, Utah; and Portland, Oregon, each moved toward buyers, while Greenville, South Carolina, and Nashville, Tennessee, reached peak-buyer status. On the other end, Hartford, Connecticut, was the only peak-seller market.
If more plentiful inventory and market leverage are the treat, then the trick is weakening affordability as mortgage rates rise.
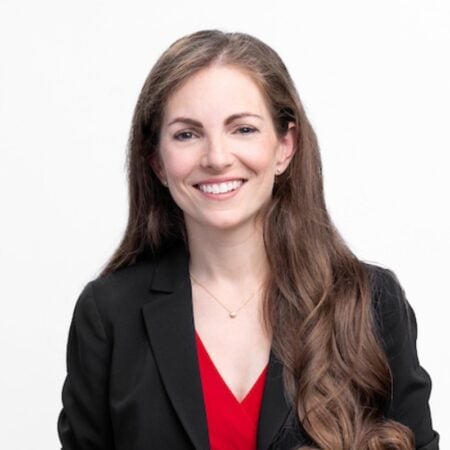
Danielle Hale
“The Market Clock tool helps buyers and sellers understand their negotiating power by bringing together housing inventory, sales, and contract activity,” Realtor.com Chief Economist Danielle Hale said on Monday. “It shows how well supply and demand are balanced and how conditions are shifting. Its latest reading shows buyers gaining ground nationally and in many markets.”
“Even so, affordability is likely to continue as a top concern for shoppers, especially as mortgage rates above 7 percent limit how much home a fixed budget can buy,” she added.
Fixed rates have made a rapid-fire ascent over the past month, breaching 7 percent on Sept. 24. The catalyst has been two-fold: the Federal Reserve’s decision to hike the federal funds rate (i.e., short-term rate) by 25 basis points and quickly rising 10-year Treasury yields.
The 10-Year Treasury Yield has the greatest impact on mortgage rates as lenders add a spread — or percentage markup — on top of it. The spread reflects the effects of monetary and fiscal policies, economic growth, inflation, higher origination costs and the gap between mortgage-backed securities (MBS) and Treasury yields.

Jake Krimmel
Rising rates have shrunk consumers’ pockets, with the jump from 6.66 percent in late August to 7.40 percent in October reducing the typical buyer’s purchasing power by $22,000. Realtor.com Senior Economist Jake Krimmel said buyers can offset mortgage pressure with shrewd negotiating, but affordability will remain a major challenge.
The portal’s economists also said homebuyers can gain financial leverage by building a budget buffer, increasing their credit score and bolstering their down payments. A better credit score yields the best results, they explained in a previous report: a borrower who raises their score from 700 to 720 saves roughly five and a half basis points on a 30-year fixed-rate mortgage.
A score of 740 yields a smaller benefit, razoring rates by 4.91 basis points.
“More buyers can negotiate in more markets, but a bigger negotiating advantage doesn’t always mean more affordability,” Krimmel said. “As rates rise, the same monthly budget supports a lower home price. Market leverage and purchasing power are moving in opposite directions right now.”