Americans are clinging to the dream of homeownership — even though their incomes are barely enough to sustain it.
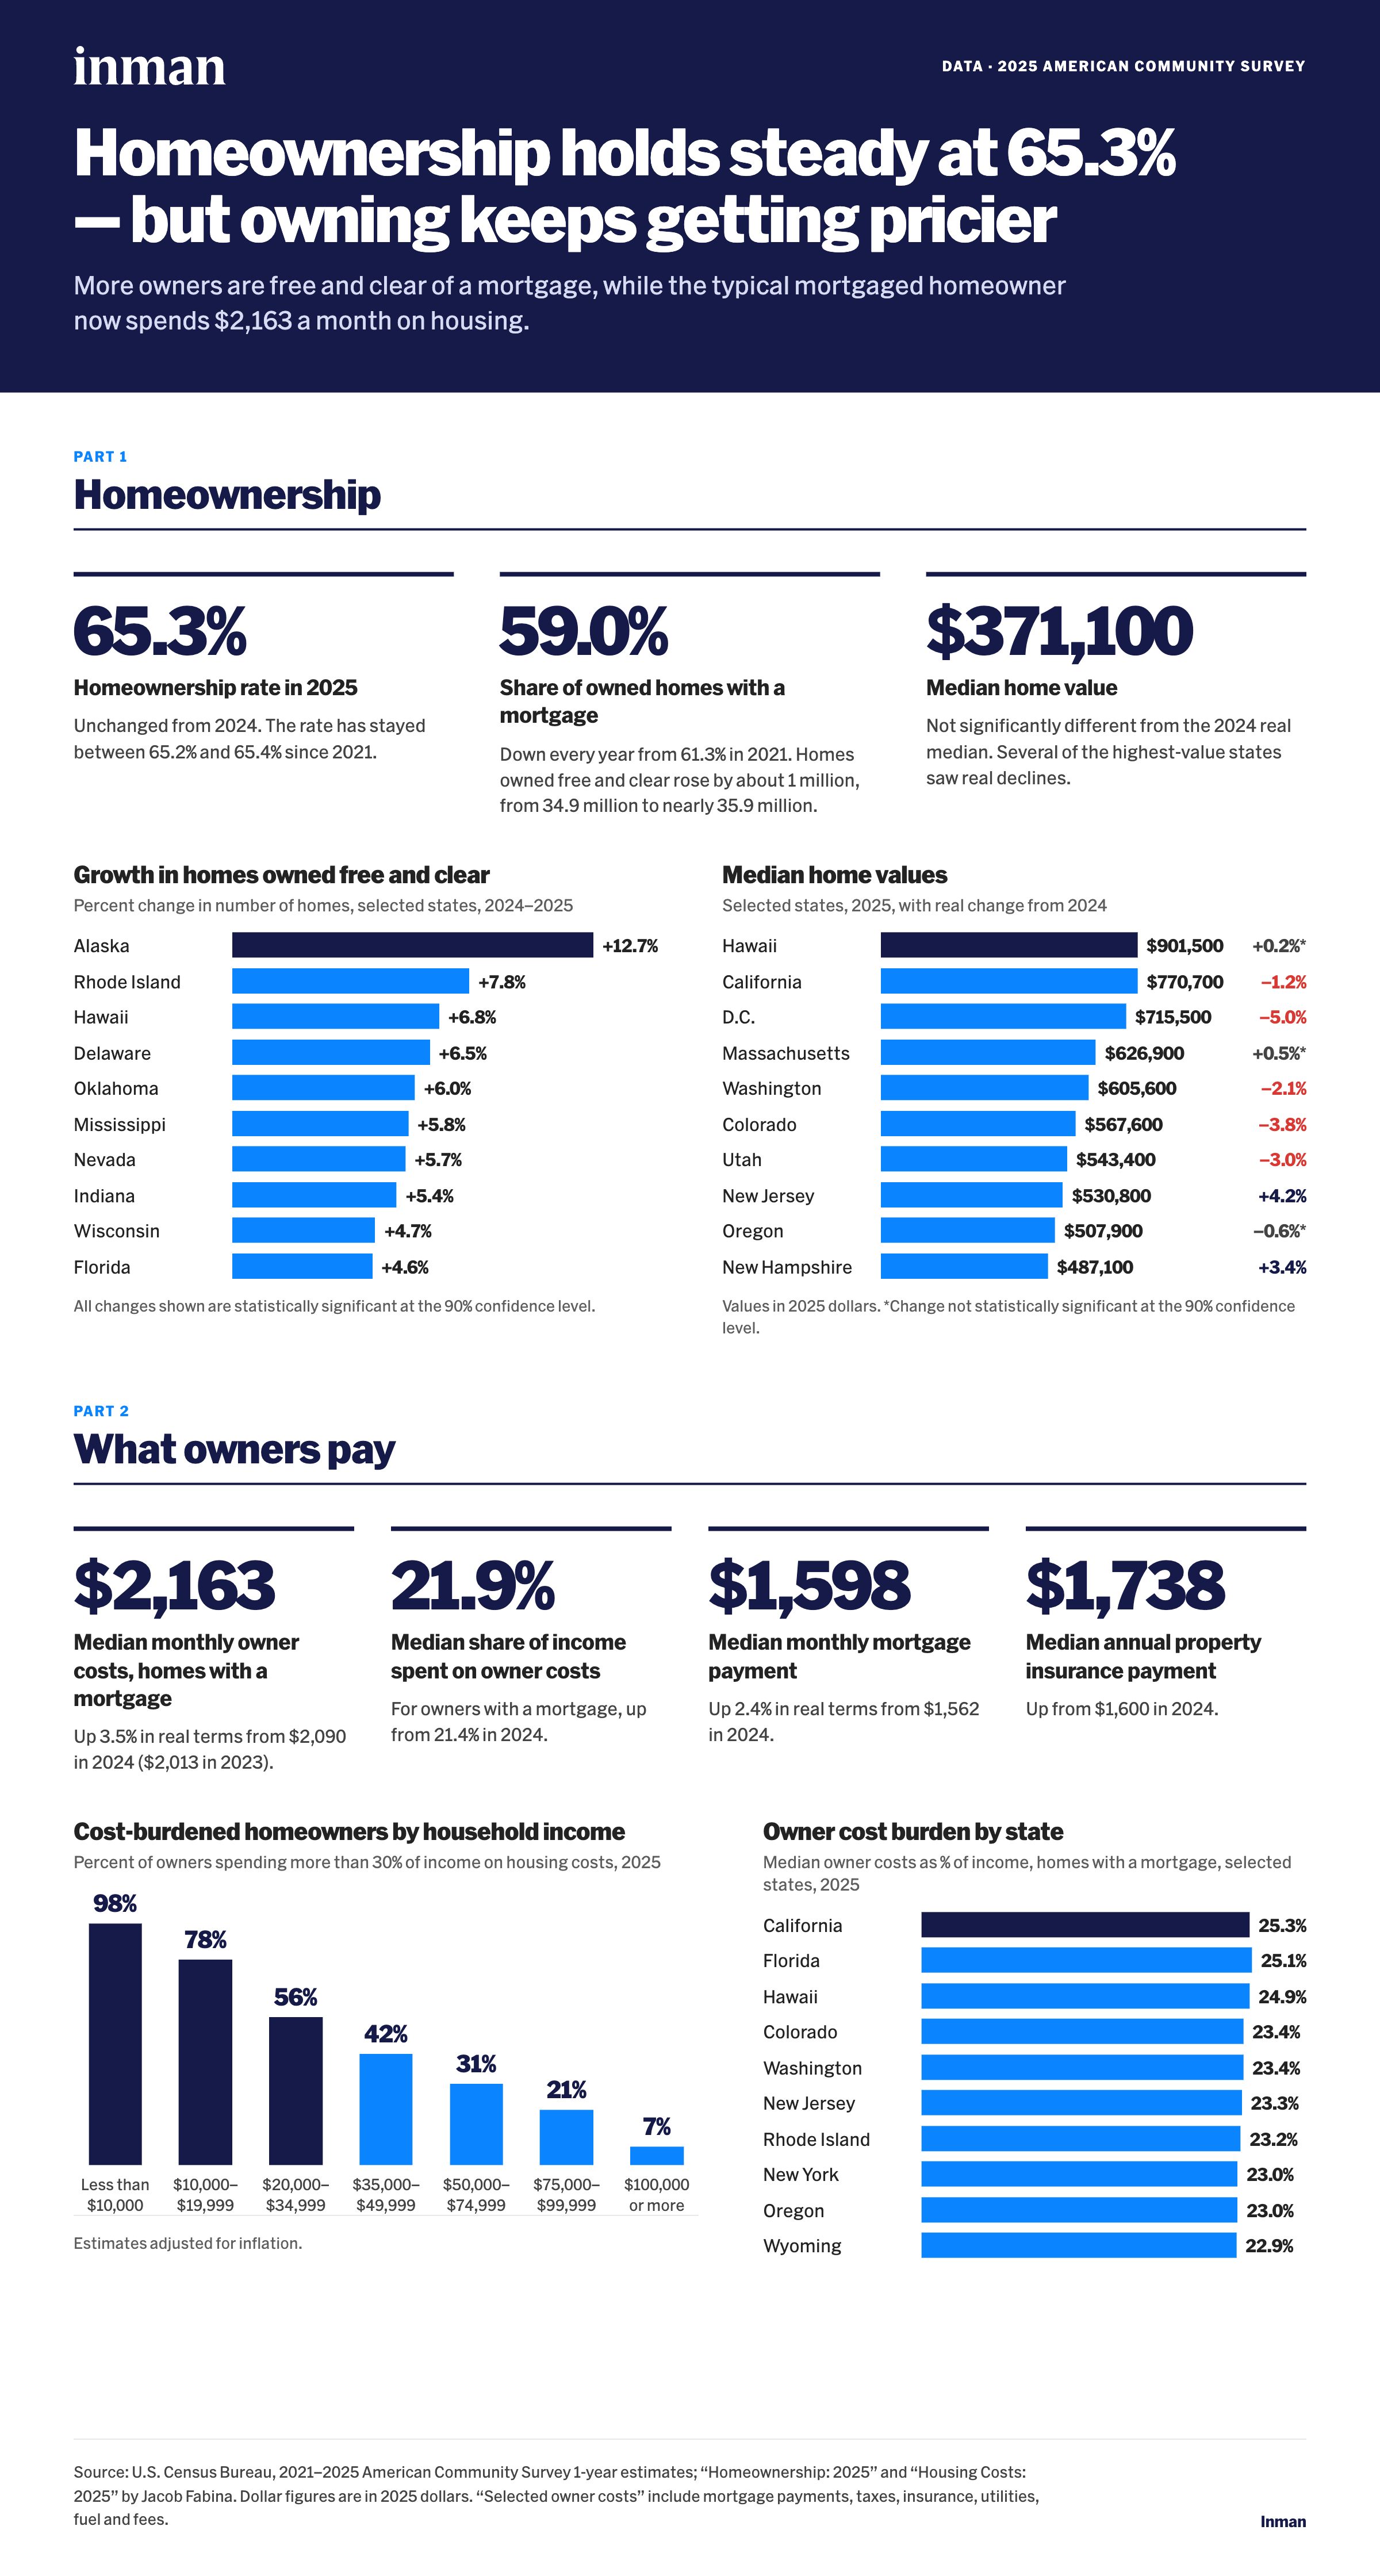
The U.S. Census Bureau released its 2025 American Community Survey 1-Year data on Thursday, which includes statistics on 40-plus topics, including housing. The national homeownership rate held steady at 65.3 percent, only 0.1 percentage points below the 5-year high of 65.4 percent. The majority of homeowners carry a mortgage (59 percent), with the real median mortgage payment increasing 2.4 percent year over year to $1,598.
Total housing costs, which may include expenses like homeowners association (HOA) fees, maintenance and repairs, increased 3.5 percent year over year from $2,090 to $2,163. Households now spend 21.9 percent of income on these costs, up 0.5 percentage points and just 8.1 points below the widely recognized 30 percent affordability threshold.
Hannah Jones
Median household incomes are edging up (+1.2 percent yoy after inflation), but Realtor.com Senior Economist Hannah Jones said it’s not enough to keep up with median home value growth.
“New 2025 American Community Survey data show median household income rose 3.9 percent to $84,780, with incomes up nominally in 49 of 50 states,” she said in an emailed statement. “But housing remained out of reach for many households. With a median listing price near $424,000 in 2025, mortgage rates averaging 6.6 percent, a 20 percent down payment, and taxes and insurance at roughly 1.7 percent of home value, a buyer needed about $110,700 to afford a median-priced home, roughly $26,000 more than the typical household earned.”
“Closing that gap would have required incomes to be 30.5 percent higher, prices about $99,000 lower or mortgage rates near 3.5 percent,” she added. “That affordability challenge has persisted, even as the year started with a promise.”
Jones said the market was primed in homebuyers’ favor at the beginning of the year, with sub-6 percent mortgage rates. However, macroeconomic and geopolitical conflicts have pushed mortgage rates up — now in the 7.30 percent range — leaving most homebuyers unable to take advantage of better inventory levels and falling list prices.
“Even assuming incomes have grown in line with recent wage gains of 3 percent to 4 percent since 2025, the typical household income would still be roughly $28,000 short,” she said. “Demand has cooled in response to higher rates, and pending sales fell 4.1 percent year over year in September, the steepest annual drop since March 2025, even as inventory approached pre-pandemic levels and prices softened.”
Data visualized with AI assistance
Realtor.com has released several reports on how homebuyers can attempt to make the math work, even as rates fluctuate. They can improve their credit scores, increase their down payments, shop lenders and build a budget buffer to help them absorb a 0.50 percent rate increase or decrease.
As for what lies ahead this year, homebuyers aren’t expected to receive mortgage rate relief.
The Federal Reserve held the federal funds rate steady (at 3.75 to 4 percent) at its Oct. 28 Federal Open Market Committee (FOMC) meeting. The federal funds rate affects how banks and financial institutions set rates, including mortgage rates, but a change doesn’t guarantee mortgage rates will move in tandem.
The 10-Year Treasury Yield has the greatest impact on mortgage rates as lenders add a spread — or percentage markup — on top of it. The spread reflects the effects of monetary and fiscal policies, economic growth, inflation, higher origination costs and the gap between mortgage-backed securities (MBS) and Treasury yields.
“Whether the Fed hikes or holds this month, homebuyers shouldn’t expect a big change in mortgage rates,” First American Senior Economist Sam Williamson told Inman on Wednesday after the Fed’s FOMC meeting. “With another hike widely expected in December and further increases possible next year, borrowing costs are likely to remain elevated, keeping many buyers and sellers on the sidelines. But not everyone has the luxury of waiting. New jobs, growing families and other life events will keep some buyers moving forward, even as higher rates delay moves that can wait.”
Jones said mortgage rates will remain “the swing factor” and will shape next year’s American Community Survey results.
“For rates to trend lower, inflation has to cool, and the latest data shows it is moving the wrong way,” she said. “Annual inflation rose to 3.7 percent in September as energy prices surged amid the conflict in the Middle East, and core inflation edged up to 2.6 percent.”
“With the Fed focused on bringing inflation back under control while protecting the labor market, a significant drop in mortgage rates is unlikely in the near term,” she added. “For buyers on the fence, though, today’s mix of more inventory, more price cuts and more room to negotiate is the best they’ve had in years.”