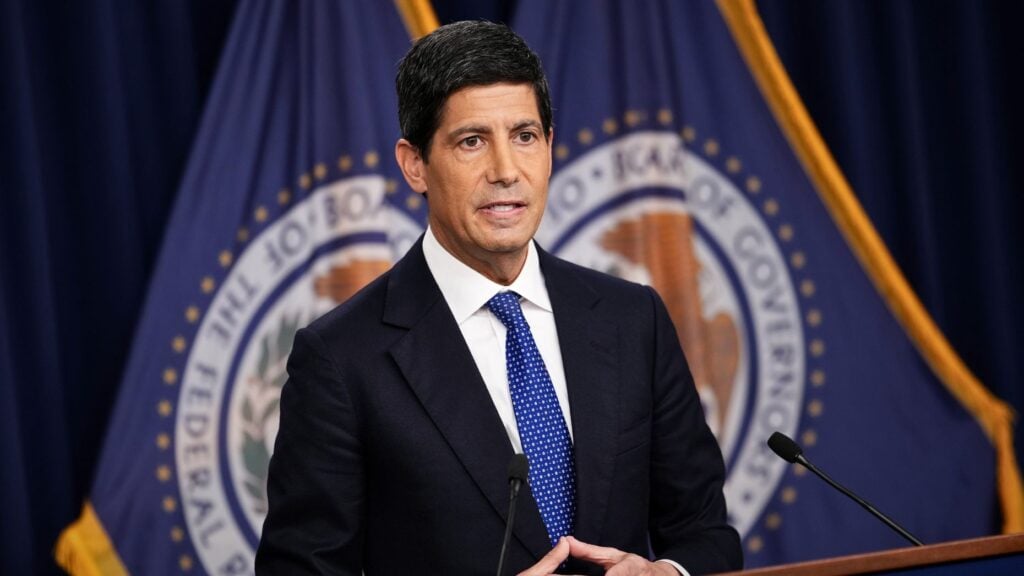
The Federal Reserve held its benchmark interest rate at 3.75 percent to 4 percent Wednesday. Housing economists said the pause will do little to lower mortgage rates, which have topped 7 percent since late September, with another hike expected in December.
The Federal Open Market Committee voted 10-2 to keep the target range unchanged, according to a statement. Fed Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented, preferring a quarter-point increase.
“Inflation remains elevated,” the committee said in the statement. “The accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee’s 2 percent goal.”
The hold follows a quarter-point hike in September.
Mortgage rates follow Treasury yields
Jeff Ostrowski, a housing market analyst at Bankrate, said in commentary that mortgage rates rose more than the Fed’s quarter-point September hike in the month that followed.
“The Fed doesn’t control mortgage rates,” Ostrowski said. “The lesson? Mortgage rates move with 10-year Treasury yields, not the federal funds rate.”
The 10-year Treasury yield fell 0.21 percentage points over the past month, according to Trading Economics. The yield slid for three weeks to one-month lows below 5 percent, as a global tech selloff pushed investors toward safer assets. It rose to 5.04 percent Wednesday after the Fed’s decision.
The 30-year fixed-rate mortgage averaged 7.32 percent the week of Oct. 22, according to Freddie Mac. That was down from 7.4 percent a week earlier and up from 6.19 percent a year earlier. Freddie Mac releases its next weekly survey Thursday.
Sam Williamson, a senior economist at First American, said in commentary ahead of the meeting that rising long-term inflation expectations could lead some policymakers to push for another hike and dissent if the committee voted to pause.
“While long-term inflation expectations remain broadly anchored, the Fed’s concern is that persistently high inflation could foster an inflationary mindset,” Williamson said. “Workers may seek larger raises, while businesses raise prices in anticipation of higher costs, creating a cycle that keeps inflation elevated.”
Williamson said buyers should not expect the Fed’s decision to move mortgage rates in the near term.
“Whether the Fed hikes or holds this month, homebuyers shouldn’t expect a big change in mortgage rates,” he said. “With another hike widely expected in December and further increases possible next year, borrowing costs are likely to remain elevated, keeping many buyers and sellers on the sidelines. But not everyone has the luxury of waiting. New jobs, growing families and other life events will keep some buyers moving forward, even as higher rates delay moves that can wait.”
Price growth hits weakest September since 2011
U.S. home prices rose 1.2 percent year over year in September, the weakest September pace since 2011, according to First American Data & Analytics’ Home Price Index, released Monday. Prices were flat from August to September.
“The recent increase in mortgage rates may further constrain affordability and strengthen the rate lock-in effect, limiting both the demand and the supply of homes for sale,” Mark Fleming, chief economist at First American, said in a statement. “Homeowners’ ability to remain in their homes and become neither a seller nor a subsequent buyer, rather than sell into a higher-rate market, continues to put a floor under prices.”
Luxury-tier prices grew faster than starter-tier prices in roughly 70 percent of the top markets First American tracks. Fleming said lower-end buyers have less room to absorb higher monthly payments, while luxury buyers are less constrained by financing costs.
Chicago posted the largest annual gain among major metros at 5.1 percent, followed by New York at 4.9 percent. Dallas posted the steepest decline at 6.3 percent, followed by Austin, Texas, at 4.3 percent.
Buyers wait out the election
Melissa Cohn, regional vice president of William Raveis Mortgage, said in commentary before the meeting that her business has slowed as buyers wait for the Nov. 3 midterm election.
“While I’m still doing business, the velocity of business is greatly diminished from where it was,” Cohn said. “We’re at a moment where a lot of people have hit the pause button, waiting to see what happens in the election.”
Cohn said affordability has stalled activity.
“The housing market is imploding,” she said. “Mortgage rates are at a point where people just can’t afford to buy, and new-home sales activity is diminishing each week. … The prices haven’t dropped enough to compensate for the higher interest rates; mortgage rates are higher than they were earlier this year, and it’s impacting affordability.”
Jacky Teplitzky, a broker with Douglas Elliman, said in commentary that renters face a choice between rising rents and negotiating on purchase prices.
“If interest rates hold steady, people will eventually recover from the shell shock they got when they came back from summer vacation and realized that interest rates had gone up, the rental market had gotten out of control and rental prices had gone through the roof,” Teplitzky said. “What choices do people have? They need to live somewhere, so will they pay these exorbitant rent prices, or will they try to negotiate down the asking prices to make up for the higher interest rates?”
Home equity rates climb after September hike
Linda Bell, a home lending expert at Bankrate, said in commentary ahead of the meeting that a hold could steady home equity rates.
“With the Federal Reserve expected to leave rates unchanged at its October meeting, this could bring more stability to home equity rates in the near term,” Bell said. “Home equity rates have been steadily on the rise since the September hike and are at their highest level in more than two years. With rates varying by lender, this makes it even more important for homeowners to compare rates and overall costs, which can help them find the best deal.”
What comes next
The Commerce Department releases the Personal Consumption Expenditures price index, the Fed’s preferred inflation measure, Thursday. The Fed’s final meeting of the year runs Dec. 8-9 and will include updated economic projections.