October was the perfect storm for existing-home sales, with a typical seasonal slowdown made worse by elevated mortgage rates, a worsening macroeconomic environment and political uncertainty.
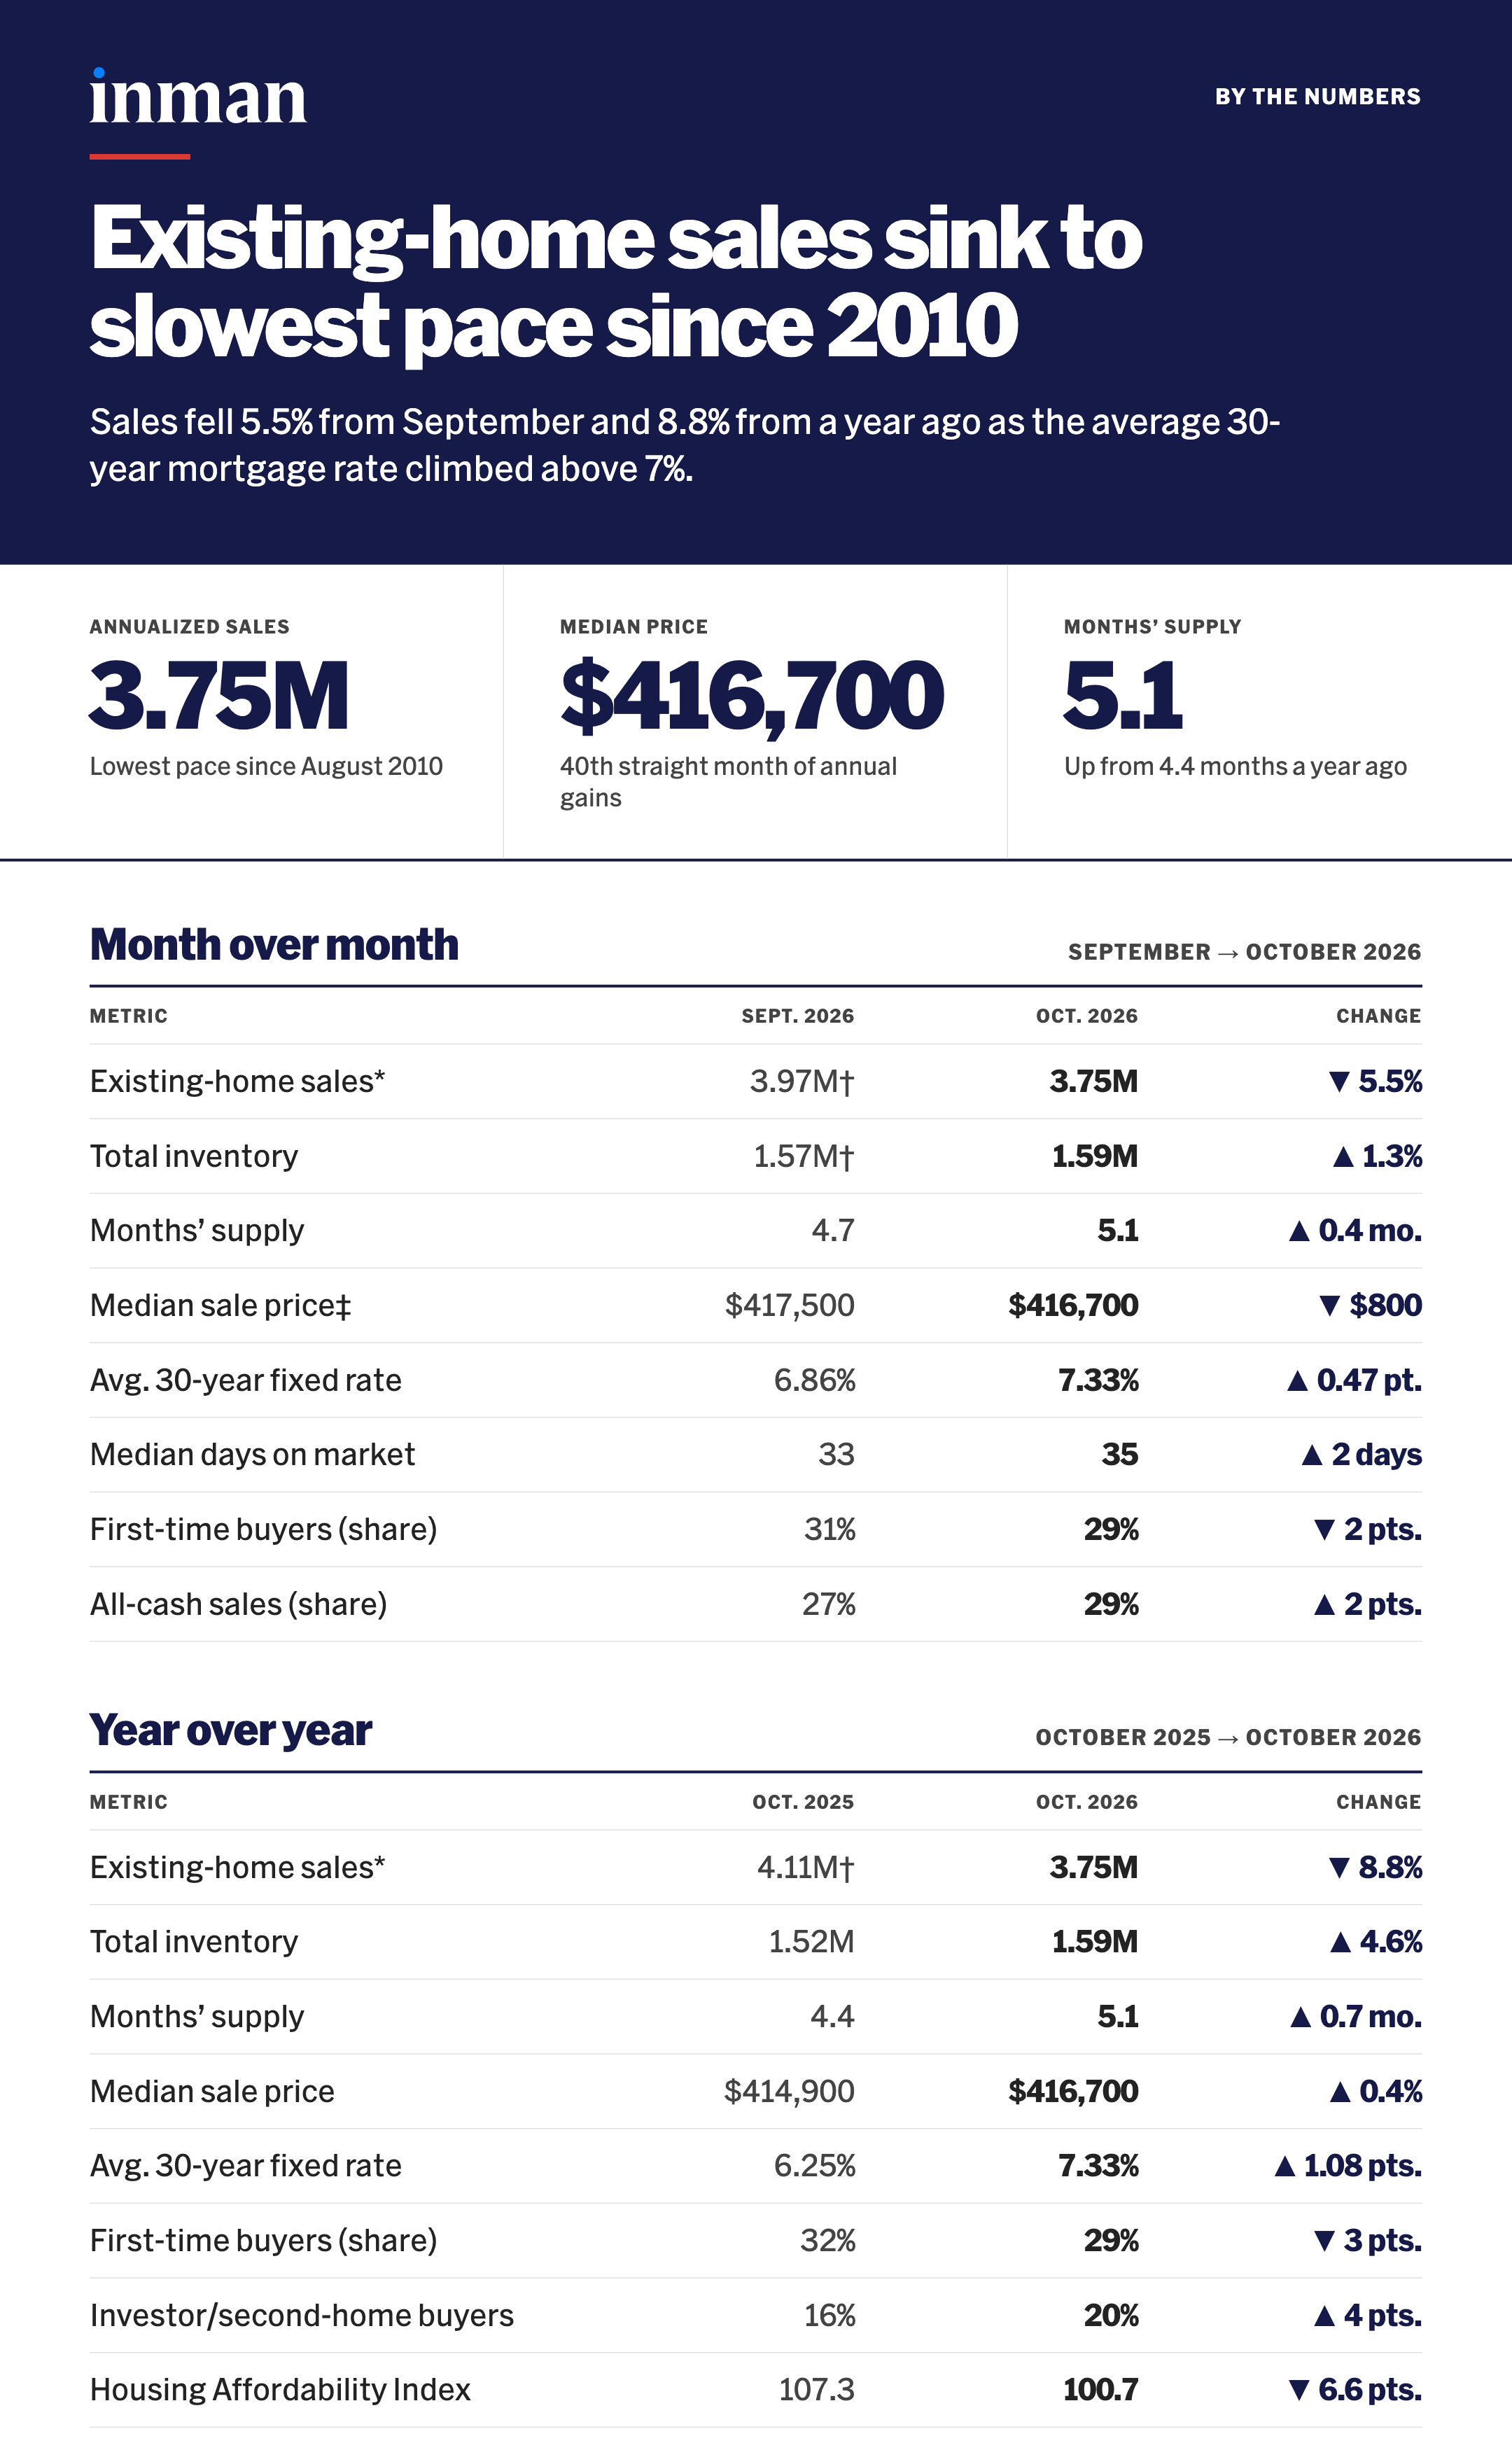
Existing-home sales during October declined 5.5 percent month-over-month and 8.8 percent year-over-year to a seasonally adjusted rate of 3.75 million, the lowest rate since August 2010 (3.68 million). Annual sales declined in all four regions; however, the Northeast was the only region to also experience a month-over-month drop.
Despite slowing sales, unsold inventory (1.59 million units) and the median home price ($416,700) increased by 1.3 percent and 0.4 percent, respectively.
Blame the mortgage rates
NAR Chief Economist Lawrence Yun said mortgage rates are the primary cause of current market woes.
Fixed rates experienced a rapid-fire ascent at the beginning of the fall, breaching 7 percent on Sept. 24 and then roughly a week later reaching a three-year high of 7.40 percent on Oct. 8. The catalyst had been two-fold: the Federal Reserve had hiked the federal funds rate (i.e., short-term rate) by 25 basis points during its Sept. 16 FOMC meeting and 10-year Treasury yields were rising at a historic pace.
Rates have since relaxed to the lower 7 percent range, but the short-term damage is already done.
“Homebuying is difficult when mortgage rates have climbed to their highest levels since 2000, aside from a single month in 2023,” Yun said in a written statement. “As a result, home sales fell to their lowest level since August 2010.”
Lisa Sturtevant
Although Freddie Mac’s Primary Mortgage Market Survey saw rates drop for the fourth consecutive week to 7.11 percent, Bright MLS Chief Economist Lisa Sturtevant said she expects mortgage rates to start rising again in the coming weeks because of sticky inflation.
“There is little reason to expect rates to come down before the end of the year,” Sturtevant said in an emailed statement. “In fact, given this week’s inflation report, it is much more likely for us to see rates increase instead of decrease.”
Yun and Sturtevant said mortgage rates will continue to impact home sales — not inventory and home price growth.
“So far, we haven’t seen higher rates lead to widespread price declines. In fact, home prices are still rising in many local markets,” Sturtevant said. “Inventory is rising, but higher rates are holding back some sellers along with buyers. Because both sides of the supply-demand equation are slowing, it’s not likely for home prices to drop significantly, even if rates move higher.”
Added Yun, “It will be the highest inventory count since November 2019. We are now back to pre-COVID inventory conditions.”
Visualized with the help of AI
Balancing expectations

Lawrence Yun
Mortgage rate volatility has pushed homebuyers to slow down or pull out of the market altogether, as shown by September’s pending home sales, which declined 7.3 percent month over month and 11.3 percent year over year.
As a result, homes are sitting on the market longer, averaging 35 days. Most homesellers, Yun said, can wait for the market to turn in their favor, thanks to strong home price appreciation.
“Despite fewer transactions in October, the 88 million homeowners across the country are largely in a comfortable financial position due to sizable housing wealth accumulation,” he said. “The number of distressed property sales remains historically low at only 2 percent of all transactions.”
However, if a homeseller is in the position where they have to sell now, due to career or family changes, they’ll need to get comfortable with making a price cut.
“If the homes are not selling at the listing price, it requires a discount,” Yun said in a pre-report call Thursday morning. “The longer the days on market, the larger the discount. If the home is sitting on the market for more than 60 days, it requires a 9 percent discount … Even with this discount that is occurring, the median home price is still squeaking out a small gain.”
How will 2026 end?
Yun and Realtor.com Chief Economist Danielle Hale said existing-home sales could improve in November and December — if mortgage rates continue to relax.
Danielle Hale
“Fortunately, the 10-year Treasury yield has pulled back from its early October highs, which has helped nudge mortgage rates below this recent peak,” she said. “However, several factors are likely to put a floor under how low rates can go.”
Hale said jobs and inflation trends will determine whether rates can move back toward the high sixes.
“[The] expected need for tighter monetary policy in the near term combined with sizable demand for capital from both governments and private companies, largely to finance AI-related investments [also matter],” she said. “Put simply, I expect to see more homebuyers come back into the market as we move away from recent mortgage rate highs, but the upside will be limited.”
Yun said rates below 7 percent could unleash a wave of untapped demand, allowing homebuyers to finally seize the advantage they’ve been given in terms of income growth, inventory and negotiating power.
“One wonders whether current price-declining markets will see buyers step in and stabilize the market,” he said. “We are not in a recession, and we are adding jobs. First part is prices, second is income growth. Wage growth is helping modestly on home affordability, but the big change is from mortgage rates. If mortgage rates can come down under 7 percent, we’ll see whether we see more buyer traffic.”
However, Sturtevant is less bullish on mortgage rates, noting that rate shifts don’t guarantee buyers the affordability break they seek. The Bright MLS economist pointed to the fact that home prices have continued rising in many markets, despite rates exceeding 7 percent.
“There is little reason to expect rates to come down further this year,” she said. “In fact, given this week’s inflation report, it is much more likely for us to see rates increase instead of decrease. Data on new pending contracts, showing activity and buyer traffic suggest that sales are going to continue to be anemic in the 4th quarter. It is very likely we will end 2026 with a total of fewer than 4 million existing home sales for the first time since the 1990s.”